
Got a leaking roof? Learn what to do immediately, how to limit water damage and when to call M&C Roofing for emergency roof repairs in Oxfordshire.
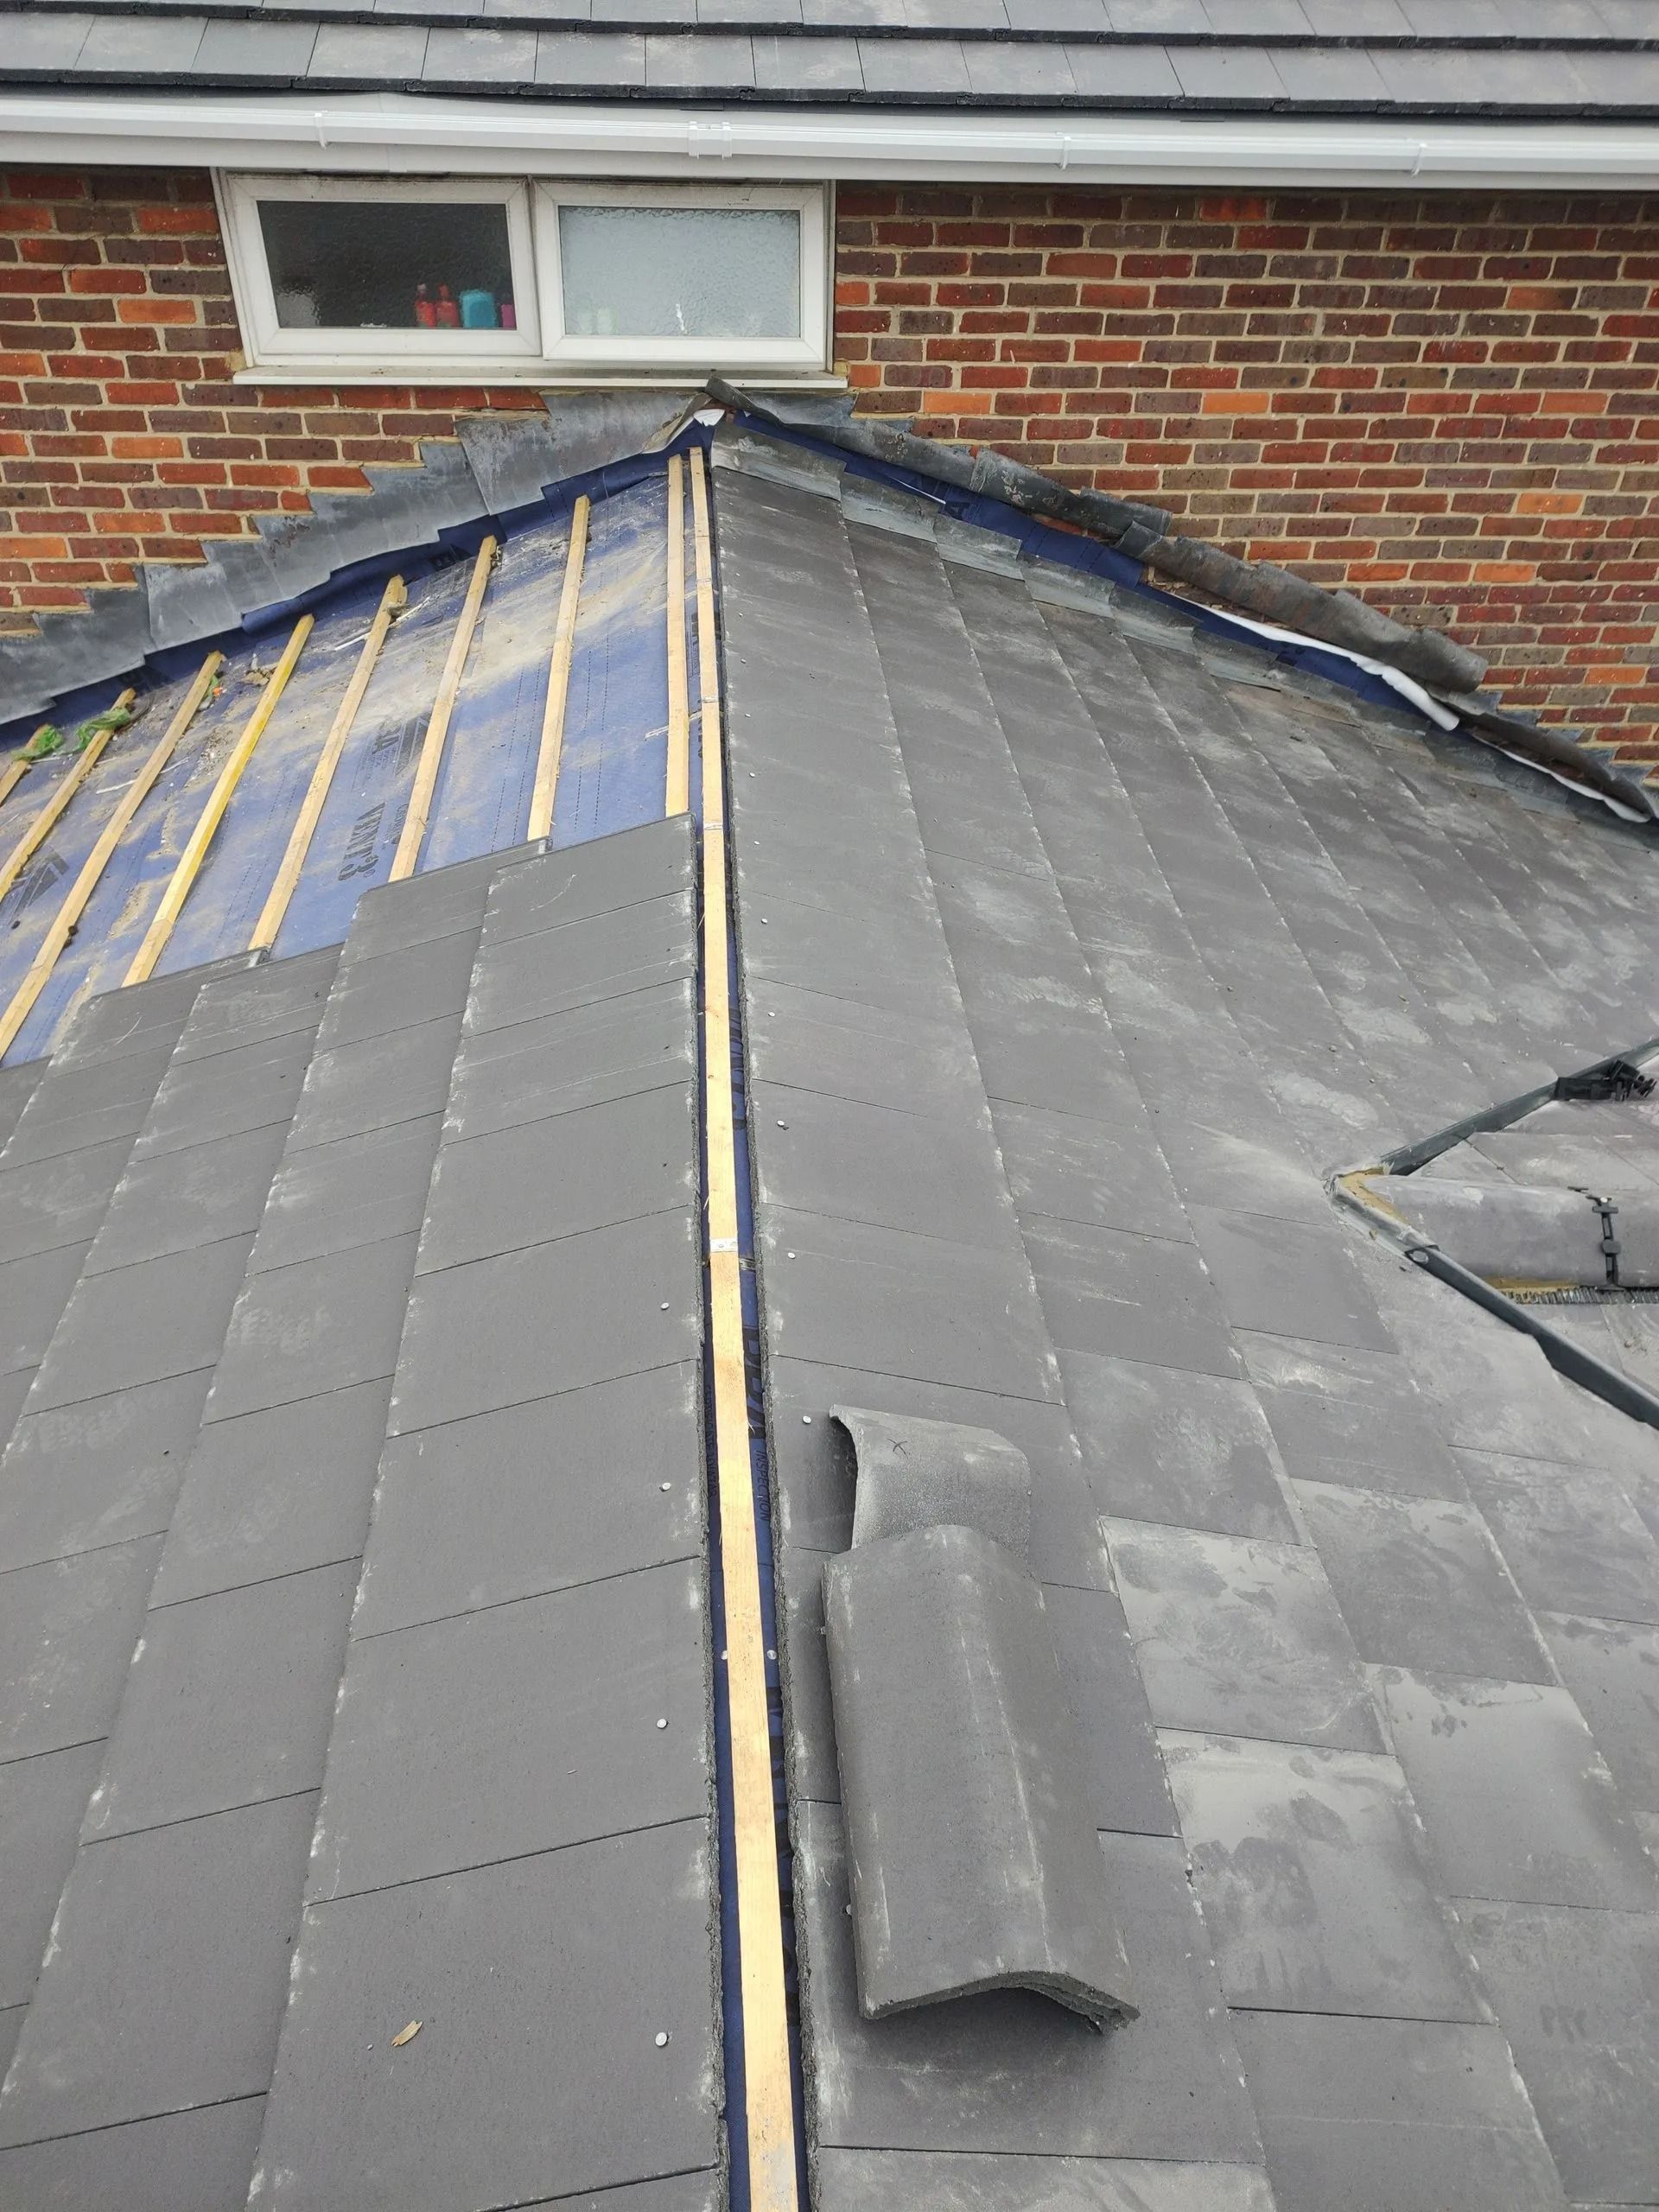
Discover why roof tiles slip, the risks of leaving them unrepaired and when to seek professional roof repairs across Oxfordshire.
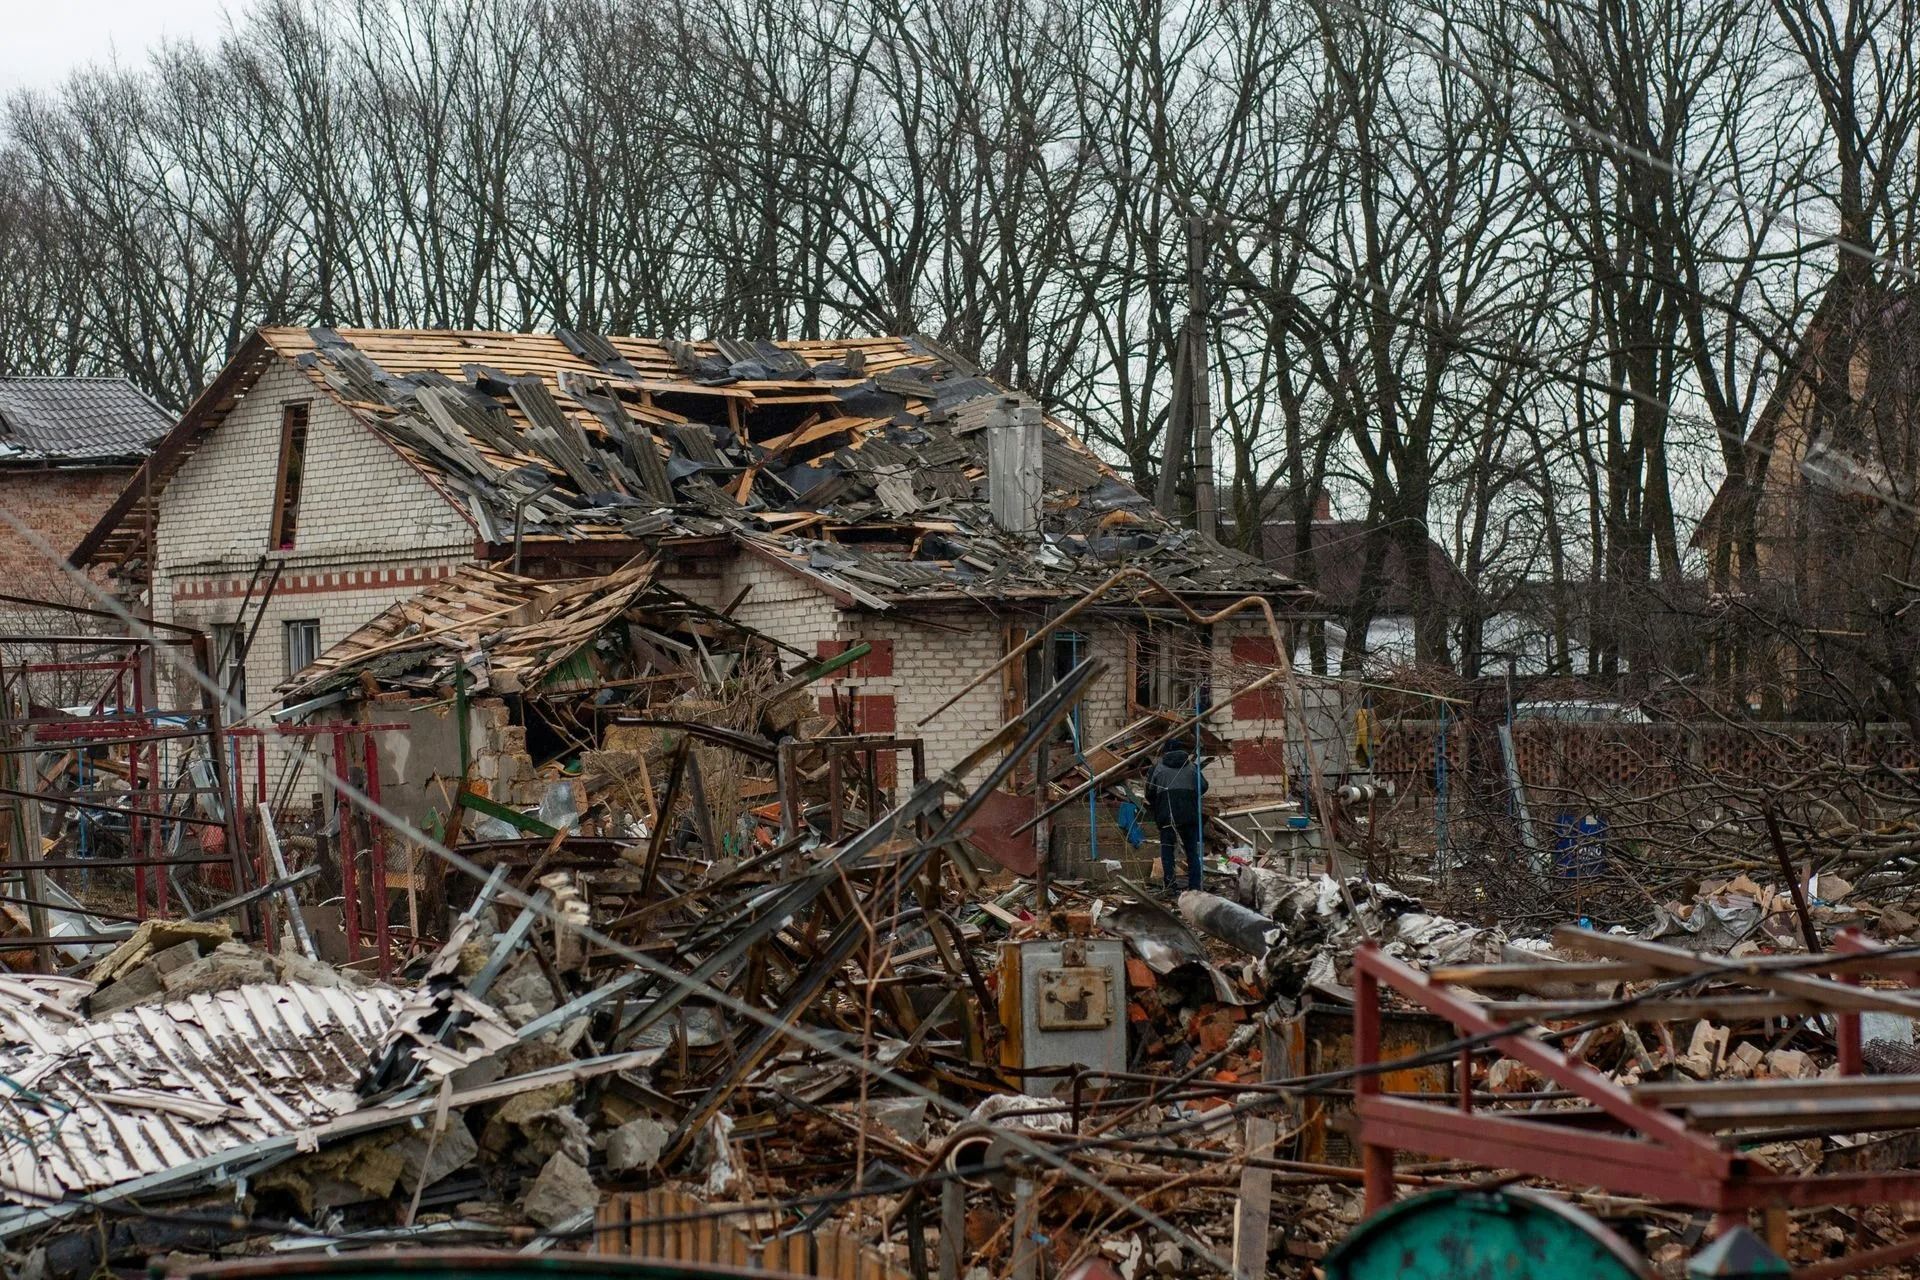
Discover what to do after storm damage to your roof. Learn how to stay safe, document damage for insurance and arrange professional roof repairs in Oxfordshire.
Get your roof ready for winter with this essential autumn roof checklist to help prevent leaks, damage and costly repairs.
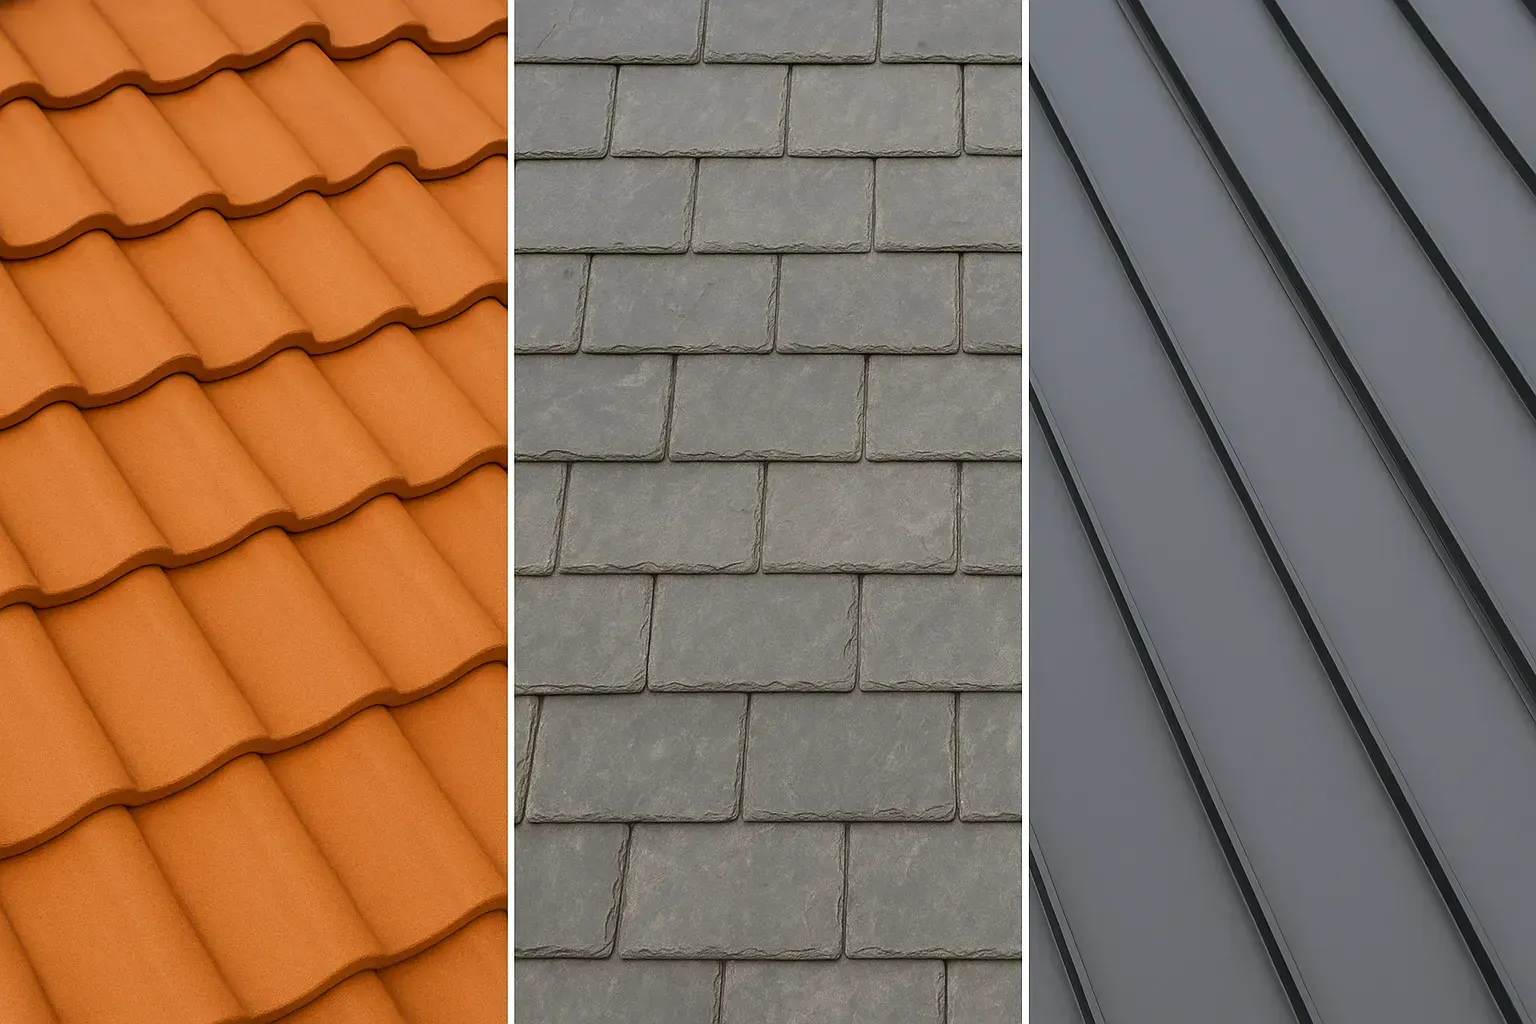
Discover 7 signs your roof may need replacing, from leaks and damaged tiles to sagging and ageing materials.
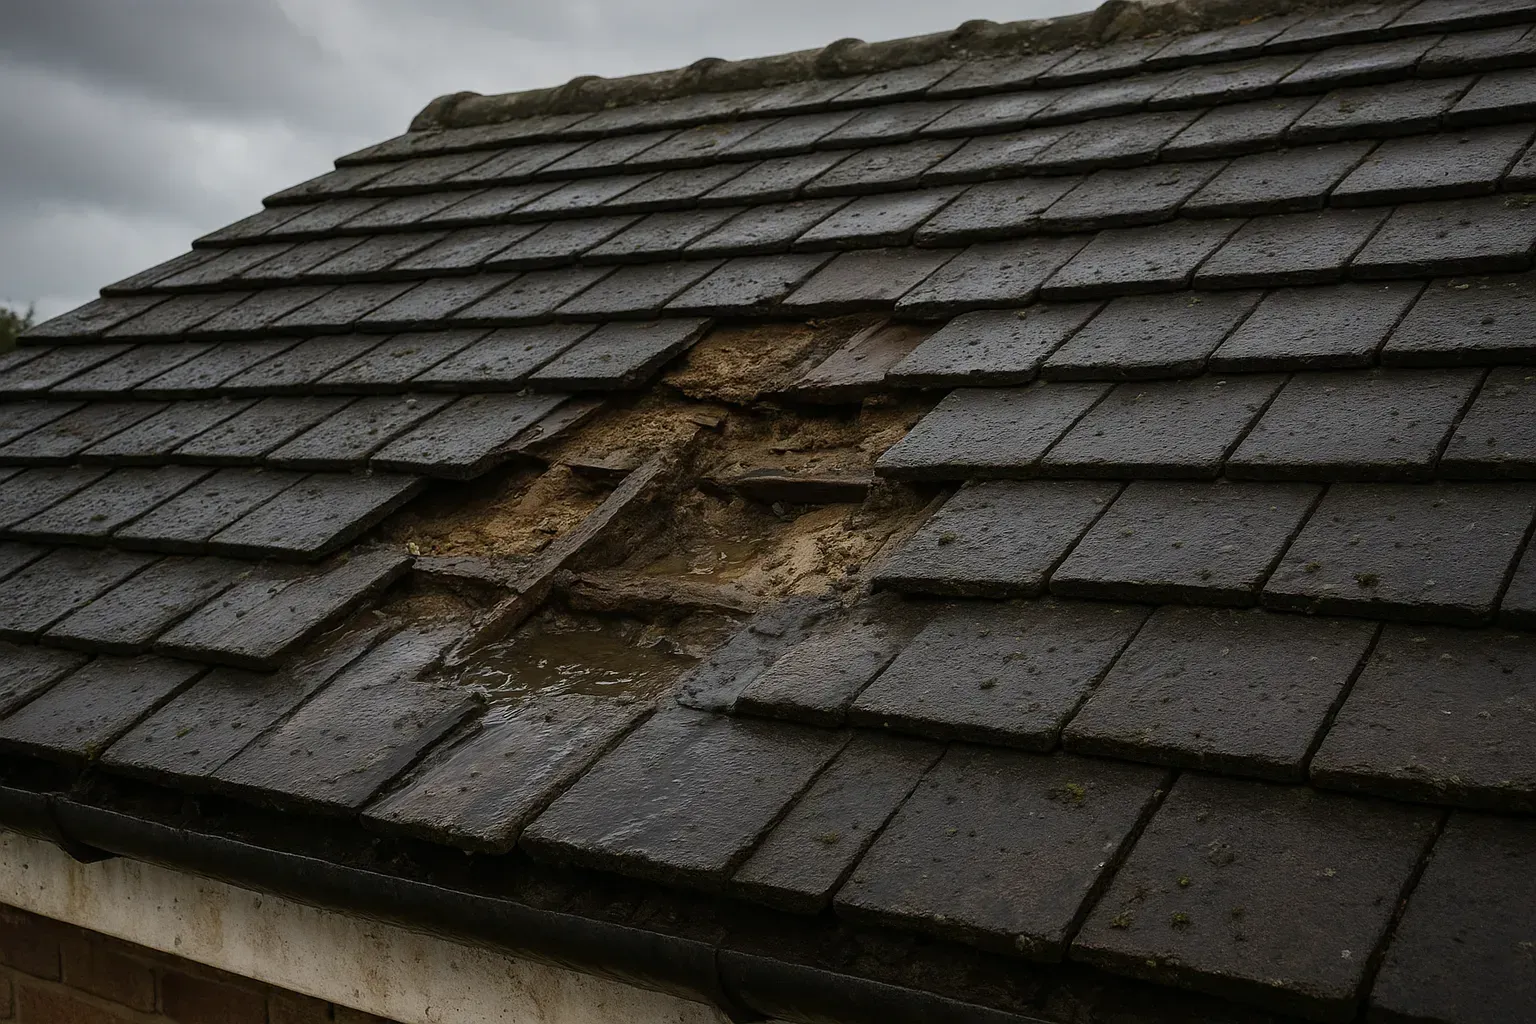
A full re-roof sounds daunting, but a well-run job is more orderly than most people expect. Most of the anxiety comes from not knowing what happens, and when. Once you understand the three steps, the process makes sense. This is exactly how we run every roof replacement we carry out for homeowners across Bicester and Oxfordshire. Step One: The Free Inspection and Written Quote Everything starts with a proper look at your roof. We do not quote from the ground or from a photograph. One of our team will get up there, check the structure, and tell you honestly what needs doing. We look at the condition of the existing covering, the state of the timbers underneath, the flashings, the ridge, the guttering, and anything else that affects how long the new roof will last. If there are problems we can see from the outside, we will tell you. If we find more once the old covering comes off, we will tell you that too, before any extra work begins. You receive a written quote that sets out exactly what is included. No vague estimates, no figures that change once we are on site. Why written? Because it protects you. You know what you are paying for before a single tile is lifted. We have worked on occupied family homes in Bicester for more than 30 years, and a clear, agreed quote is the foundation of a job that goes smoothly for everyone. There is no charge for the inspection, and no obligation to go ahead. If you decide the time is not right, that is fine. Step Two: The Work Itself Once you accept the quote and we agree a start date, the job moves in a clear sequence. Scaffolding goes up first. For most pitched roof replacements, scaffolding is needed. This is standard practice and keeps our crew safe while they work. It also protects your property. We arrange the scaffold erection before work begins, so the roofers are ready to start on day one. The old covering comes off. The existing tiles, slates, or felt are stripped back carefully. We use rubbish chutes or controlled lowering to bring material down without damaging your garden, paths, or brickwork. Skips are positioned to keep the site tidy as we go. The structure is checked. With the covering removed, we inspect the roof timbers. If any rafters or battens need attention, we deal with that before anything goes back on. This is the stage where any hidden problems become visible. We will always talk to you before carrying out work beyond what was quoted. The new covering goes on. Battens are fixed, new felt or membrane is laid, and the tiles or slates are fixed in place. Ridge tiles, hip tiles, and any leadwork are completed as part of the job. We do not leave a roof half-finished overnight if we can help it. Guttering, fascias, and flashings are finished. These details matter. A new roof covering with failing flashings or blocked gutters will cause problems within months. We make sure the whole system works together. How long does a roof replacement take? This is the question we hear most often, and the honest answer is that it depends on the size and complexity of the roof. A standard semi-detached house in Bicester or a typical Oxfordshire terrace will usually take three to five working days for the roof itself, once scaffolding is in place. A larger detached property, or one with dormers, a complex ridge line, or chimneys, may take a week to ten days. Scaffolding is usually up for a day or two before work starts and comes down a day or two after we finish, so allow for that in your overall timescale. We work on occupied homes. You do not need to move out. There will be noise during working hours, and you will see activity outside, but the inside of your home is unaffected. We aim to leave the site tidy at the end of each day. Rubbish is cleared, tools are stored, and access to your front door and garden is kept clear. Our crews are respectful of the fact that this is your home. We have been working in people's houses and gardens across Oxfordshire for a long time, and we know that how a job is run matters as much as the finished result. Step Three: Sign-Off and Your Written Guarantee When the work is complete, we do a final walk-round with you. We want you to see the finished roof, ask any questions, and be satisfied before we pack up. We go through what was done, point out anything worth knowing for the future, and make sure you are happy with the tidiness of the site. The scaffold comes down once we are confident everything is right. Your written guarantee covers our workmanship. If something we did causes a problem, we come back and put it right. That is a commitment in writing, not just a verbal promise. We are fully insured as well, so you have proper protection throughout the job and afterwards. We have been trading under the M&C name for 20 years, and the same family has worked on Oxfordshire roofs for more than 30. Our reputation is built on jobs that are done properly and on customers who feel looked after. A written guarantee is part of that. Keep the paperwork somewhere safe. If you sell your home, a guarantee from a reputable local contractor adds weight to your property's history and can be passed on to a buyer. A re-roof is a significant job, but it follows a clear path. A thorough inspection, a well-run few days on site, and a signed-off finish with a written guarantee. That is what you should expect from any contractor you choose. To book your free, no-obligation inspection and written quote, get in touch with our team through our contact page.
Looking for a trusted roofer in Bicester? Learn how to choose a reliable roofing contractor, spot rogue traders and protect your home with confidence.
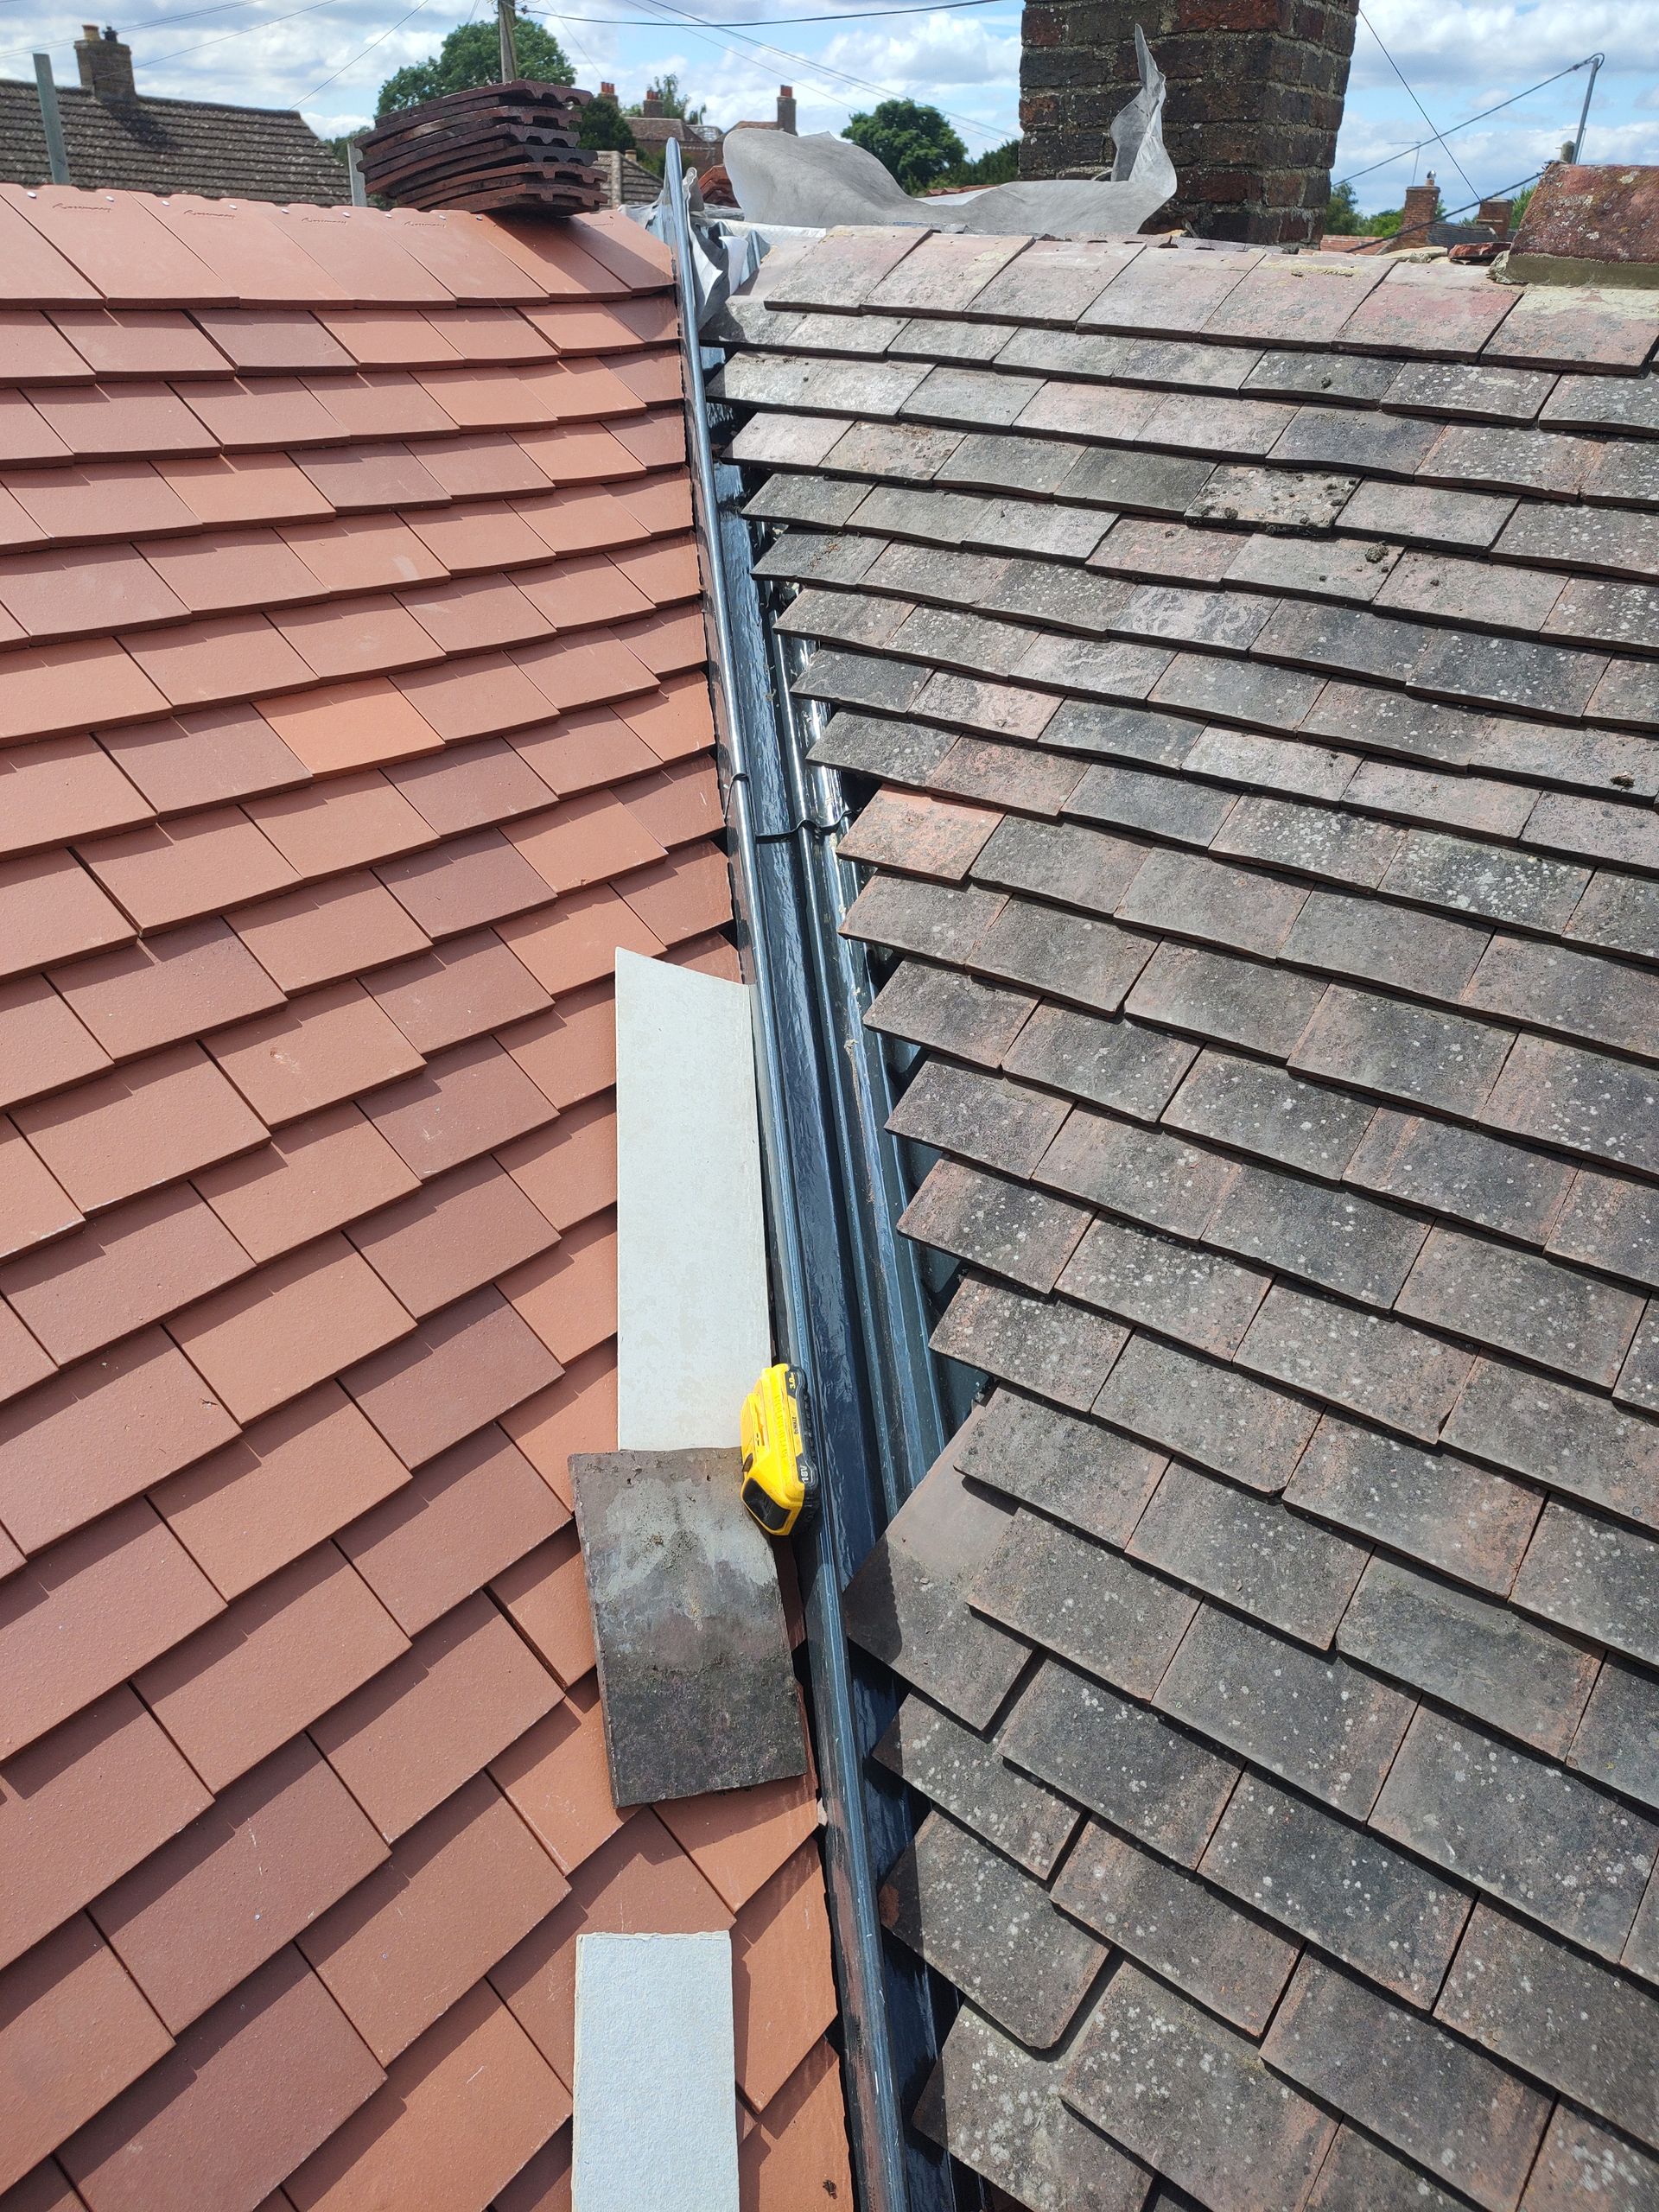
Not sure whether your roof needs repairing or replacing? Learn the key signs, understand your options and book a free roof inspection with trusted roofing specialists serving Bicester, Thame, Oxford and Oxfordshire.
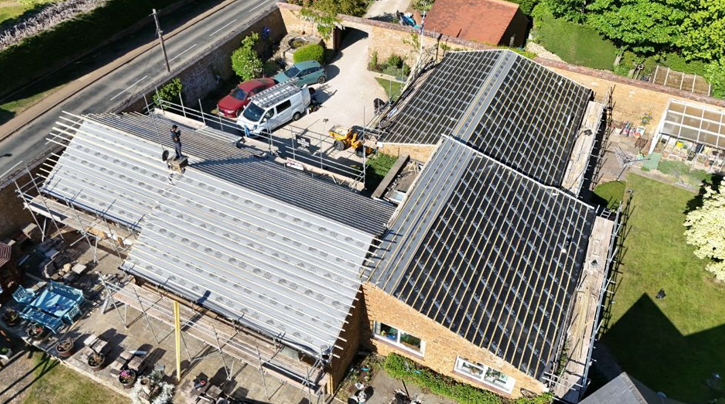
Planning a new roof in Oxfordshire? Discover realistic 2026 cost ranges for re-roofing. Book your free, no-obligation inspection with M&C Roofing today.